
Bringing together research expertise in finance, quantitative analysis,
and artificial intelligence.
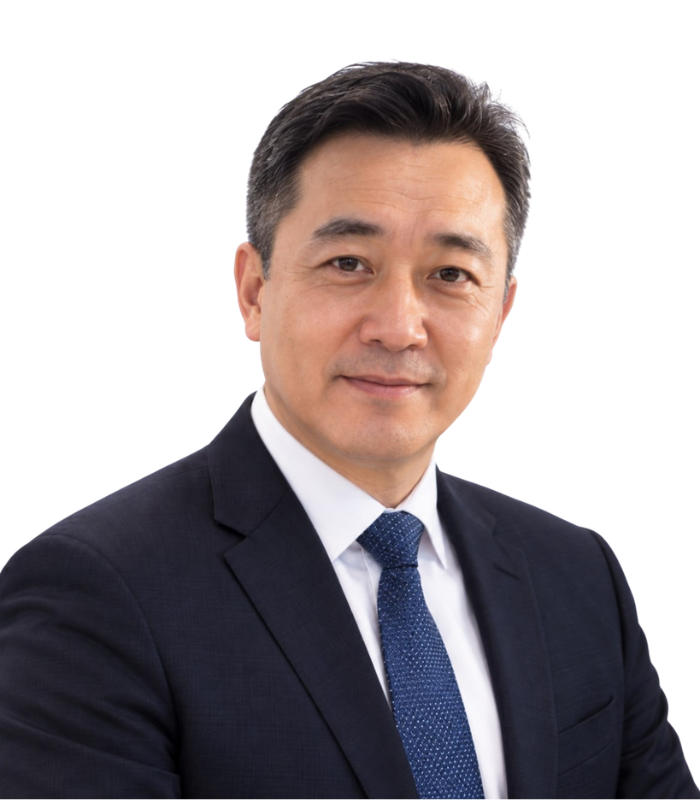
Adrianzhi Kuan Ong(王志宽)
Dean
Mr. Adrianzhi Kuan Ong possesses over 25 years of experience in international finance and asset management, with a career spanning Singapore, the United States, and Japan. He has long focused on global investment, quantitative strategies, portfolio management, and risk management.
His professional background encompasses traditional asset management, global investment strategies, and systematic quantitative investment research; he also maintains a continuous focus on digital asset market structures, quantitative trading, and risk management. Since November 2024, Mr. Ong has served as the Project Lead and Head of R&D for the Pinnacle AI Quantitative Investment System. In this role, he oversees project development, testing, and implementation, focusing on research into AI quantitative strategies, machine learning models, alpha signals, market data analysis, strategy backtesting, portfolio optimization, and risk management systems.
His current research centers on the deep integration of artificial intelligence and quantitative investment, exploring the application of machine learning, big data analytics, and systematic investment strategies within global capital markets and digital asset markets.
CORE EXPERTISE
- Global Quantitative Investment
- AI & Machine Learning
- Portfolio Optimization
- Risk Management
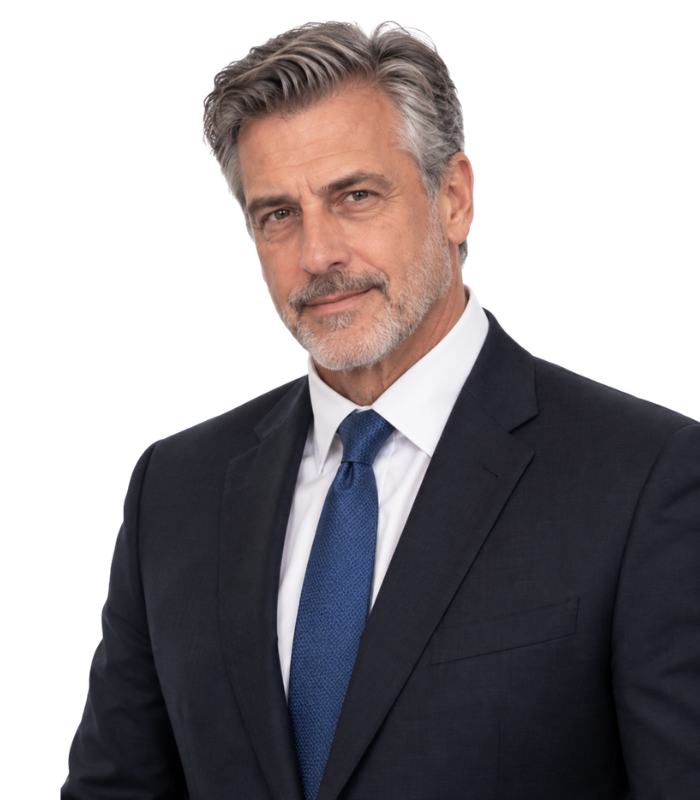
Robert Alexander Thompson
Vice Dean
Mr. Robert Alexander Thompson is a seasoned U.S. expert in investment management and quantitative research, boasting over 35 years of experience in global financial markets. His career spans traditional asset management, global macro investing, quantitative research, and fintech, with extensive involvement in researching major capital markets across the United States, Europe, and Asia.
His professional background encompasses portfolio management across equities, fixed income, foreign exchange, and global multi-asset classes, alongside long-standing research into cross-market asset allocation and risk management. From 2016 to 2023, his research focus expanded to include artificial intelligence, machine learning, and the application of financial data, with a particular emphasis on financial time series, quantitative models, and automated investment systems.
In 2024, Mr. Thompson joined the “Dianfeng” AI quantitative investment system R&D project. He currently serves as Senior Head of AI Quantitative Research and Deputy Dean of the Dianfeng AI Finance Research Institute. His responsibilities include overseeing the research framework for AI quantitative models, financial data training systems, strategy model evaluation, and risk control, as well as participating in model validation for global equities, foreign exchange, indices, and multi-asset markets.
CORE EXPERTISE
- AI Quantitative Research
- Multi-asset investment
- Financial data modeling
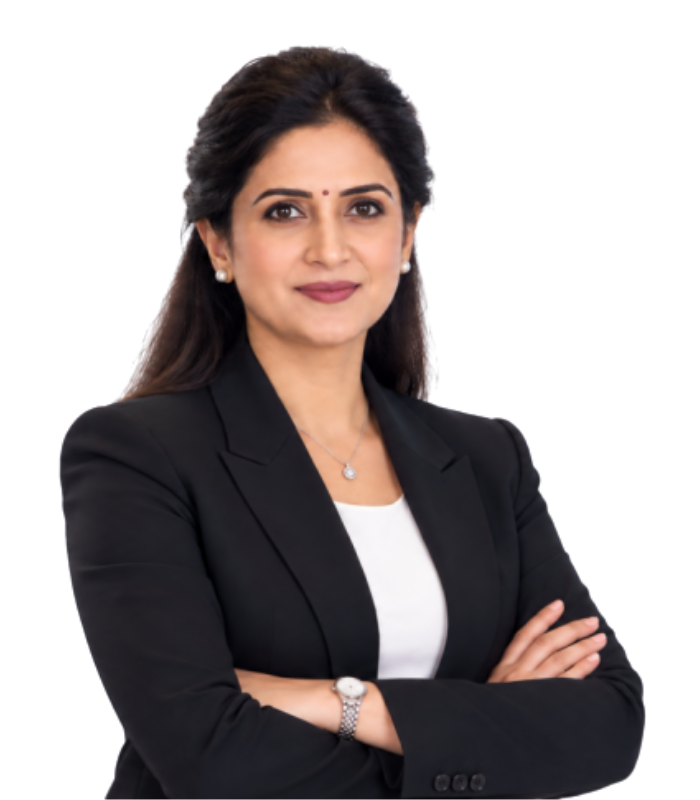
Anika Sharma
Vice Dean
Ms. Anika Sharma is a seasoned investment researcher with approximately 15 years of experience in international financial markets. Her career has been primarily based in the United States, with a long-standing focus on global equities, quantitative investment, and financial data research across major capital markets in North America, Europe, and Asia.
Her professional background spans equity research, global equity investment management, and the development of quantitative strategies. She has been involved in research across the technology, financial, and consumer sectors, as well as in global equity portfolio construction, financial time-series analysis, factor modeling, and the development of automated strategies.
In 2024, Ms. Sharma joined the development project for the Pinnacle AI quantitative investment system as a core team member. Her work focuses on global equity market data analysis, quantitative factor research, machine learning model training, and strategy backtesting, with specific responsibility for model validation across US, European, and Asian equity markets.
CORE EXPERTISE
- Global Equity Research
- Quantitative Factors
- Machine Learning
- Strategy Backtesting
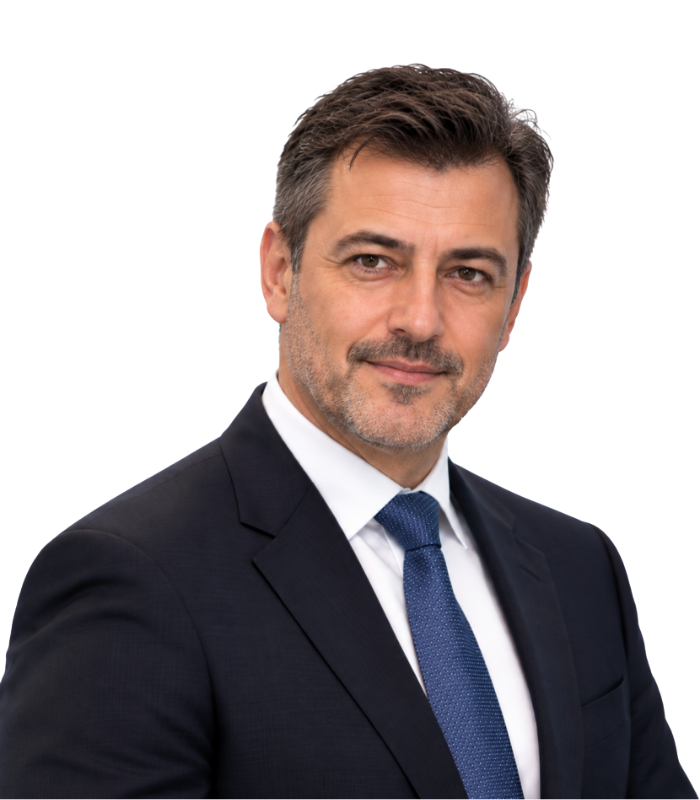
Lucas Hjortsberg
Vice Dean
Mr. Lucas Hjortsberg is a senior Swiss investment professional with over 20 years of international asset management experience. His career spans markets in Switzerland, Europe, and the United States, with a long-standing focus on research into global macroeconomics, multi-asset allocation, fixed income, and foreign exchange (FX) investments.
His professional background encompasses fixed-income research, global macro investing, and multi-asset portfolio management. He has consistently monitored global trends in interest rates, inflation, monetary policy, and FX markets, while also contributing to the development of macro-factor models, asset allocation frameworks, and systematic investment strategies.
In 2024, Mr. Hjortsberg joined the R&D team for the Peak AI quantitative investment system as a core member. He is primarily responsible for research into global macro data, asset allocation models, and FX and interest rate strategies, while also participating in the training, backtesting, and risk validation of AI models for global multi-asset markets.
CORE EXPERTISE
- Global Macro
- Multi-asset allocation
- FX and interest rate strategies
- Risk models